
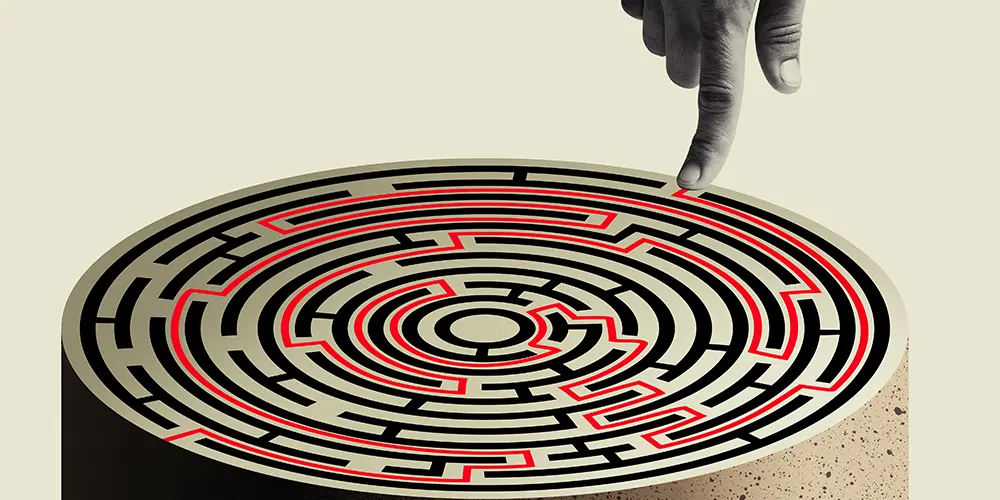
According to the old parable, a frog placed in tepid water that is heating slowly lingers until it is too late and boils to death. Is the parable applicable to the future of independent central banks?
Central bank independence is essential for achieving sound inflation outcomes. It is a global public good, absolutely worth preserving. But even if central banks stress that they are responsible for achieving their mandates, they do not operate in a vacuum and cannot achieve their objectives alone. Monetary and fiscal policies are interconnected, though that is no reason to compromise central bank independence.
Fiscal policy in particular is a key determinant of economic outcomes. Economies are often institutionally structured to separate monetary and fiscal policy – central banks are responsible for monetary policy; Treasuries and parliaments for budgets.
But large fiscal deficits and debt can boost aggregate demand and inflation, causing central banks to hike interest rates. They can push up yields and boost debt-servicing costs, creating political and fiscal pressures for central banks to cut rates, engage in yield curve control or bond buying, or undertake financial repression to limit debt-servicing costs. As President Donald Trump put it in a 2025 Truth Social message – ‘Fed should cut Rates by 3 Points. Very Low Inflation. One Trillion Dollars a year would be saved!!!’
Higher unsustainable rates due to poor economic policy or heightened rollover risks can create financial market instability, compelling central banks to inject liquidity to steady financial conditions despite poor fundamentals that aren’t being fixed. Political uncertainties, inflation persistence and unsustainable debt dynamics can drive up the term premium and crowd out private investment, undermining efficiency.
Withstanding external pressure
Whether central banks can withstand pressures from political and fiscal authorities in such circumstances is not a given, as history has amply shown. President Richard Nixon’s pressure on the Arthur Burns Federal Reserve is a preeminent example.
As a general proposition, central banks avoid commenting on fiscal policy. They may briefly mention that fiscal policy is unsustainable. But they often argue that speaking about fiscal stabilisation policy is beyond their remit, notwithstanding monetary policy impacts. They further aver that doing so may embolden politicians to speak about monetary policy. It’s better to stay in their lane. Of course, politicians are not shy anyway about flaunting their views on monetary policy.
In the US, Trump’s crusade against Fed independence undoubtedly compounds Fed hesitancy to utter the word ‘fiscal’.
But fiscal and financial dominance are undeniably rising realities with the potential to undermine central bank independence. Can the Fed in the face of sharply rising yields, continued supply shocks and Trump breathing down its neck, seeking to overhaul the Fed Board, ignore the pressures on the institution? Can the European Central Bank really just say that France must solve its fiscal problems when France’s bond market is the largest in Europe and the potential for contagion is great? Can one really believe that the Bank of Japan’s slow march to normalisation has not been influenced by Japan’s already high debt and concerns over the potential for soaring debt-servicing costs?
Of course, in the US’s case, the Fed could simply ignore such pressures, adjusting monetary policy strictly in line with its mandate. The same applies for the ECB and BoJ. But is that so easy and realistic?
A duty to the public
Central banks should be economic consciences for the nation. They are staffed with top-flight officials and first-rate economists who understand the interplay between fiscal dynamics and monetary policy and economic outcomes. As I have argued previously, the fiscal chickens are coming home to roost.
Central banks owe it to society to somewhat step out of their comfort zones, educate the public, responsibly speak truth to power and call out fiscal woes more explicitly, if nothing else making clear the ramifications for monetary policy and short and long rates.
It is perhaps a poisoned chalice. Even if doing so provokes political firestorms, especially in the US, speaking up may ultimately help protect independence. The alternative is that central banks run the risk of being overwhelmed by fiscal shortcomings, losing independence and ending up like the boiling frog.
Mark Sobel is Vice Chair and Chief Economist of OMFIF.
Join OMFIF on 21 October for a lecture with Andrew Bailey, governor of the Bank of England, on central bank independence.
Interested in this topic? Subscribe to OMFIF’s newsletter for more.